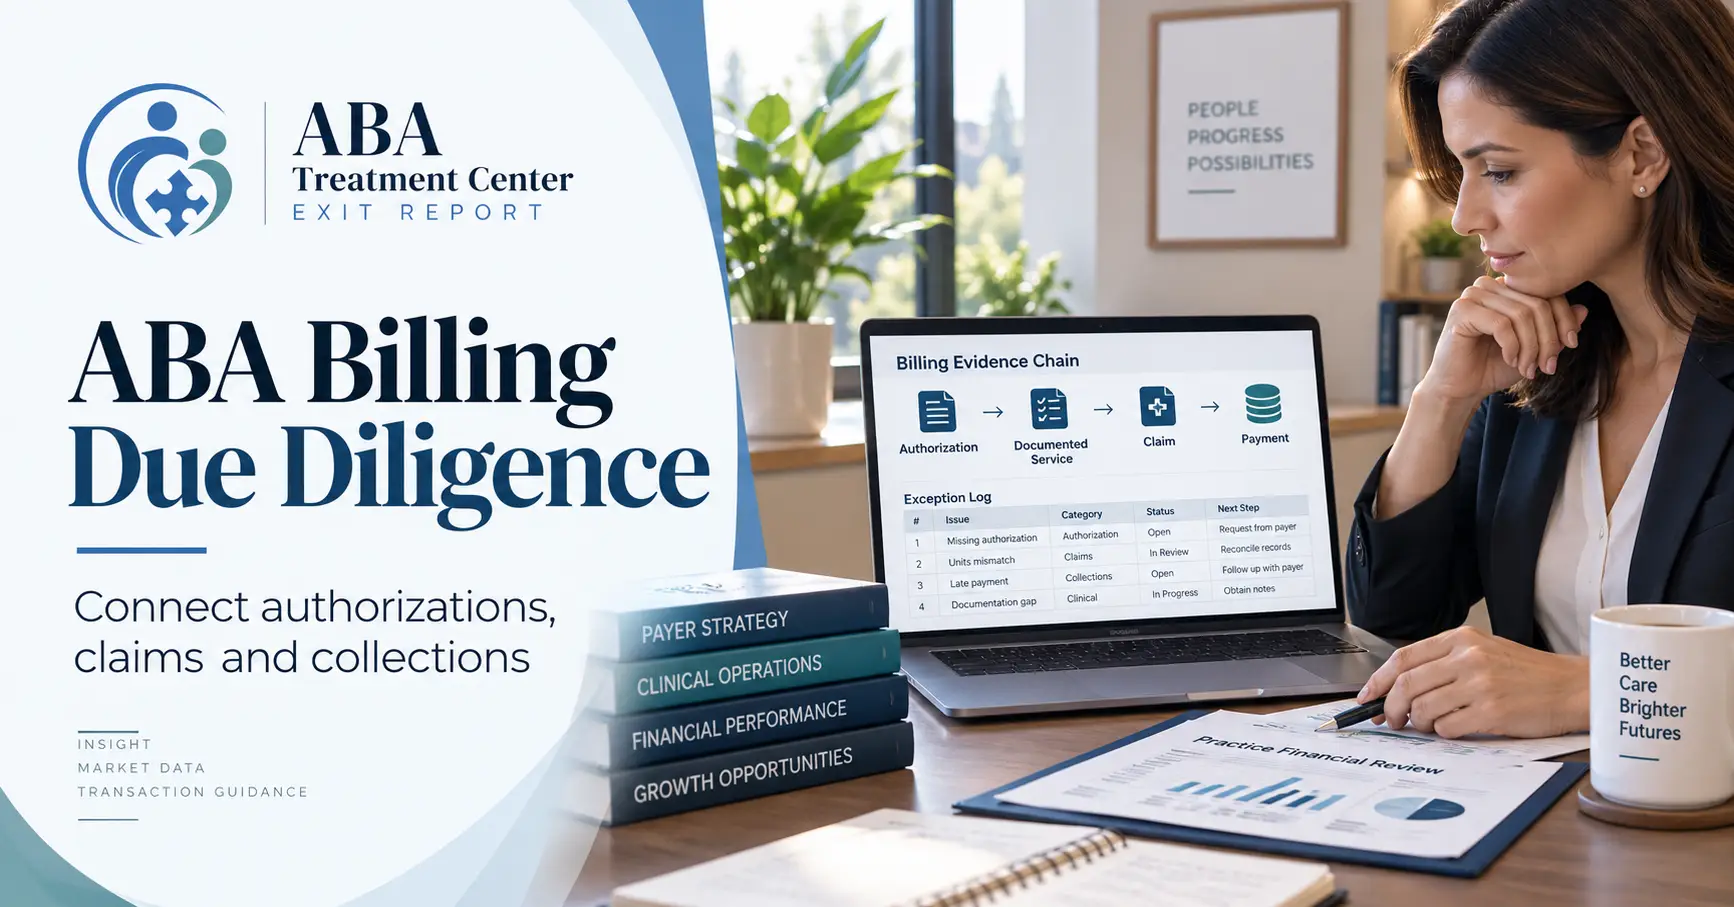
| QUICK ANSWER ABA billing due diligence should connect authorization, documented services, submitted claims and cash received. Prepare a traceable evidence chain, explain exceptions and distinguish uncollected balances from confirmed revenue. Share detailed records only through an appropriately reviewed privacy process. The objective is to help a buyer understand earnings quality and unresolved exposure without overstating what the records prove. |
A clean report is not the same as a clear answer
ABA billing due diligence becomes difficult when several systems describe the same work in different ways. The scheduling system shows a session, the clinical record documents services, the billing platform shows a claim and the bank shows a payment. A buyer wants to understand how those records fit together.
You do not need to pretend there are no exceptions. You do need a repeatable method for finding them, explaining them and identifying what remains unresolved. A tidy dashboard with no traceable support can create more questions than an honest exception log.
This article is for practice owners preparing evidence for a potential sale. It is not a coding manual, a payer policy summary or legal advice on repayment obligations. Use your billing team, clinical leadership, accountant and qualified counsel to adapt the work to your contracts and circumstances.
Start ABA billing due diligence with a defined period
Choose the period being reviewed and document the reporting basis. Service date, claim submission date, payment date and accounting recognition date are different. Comparing totals without distinguishing them can make an ordinary timing difference look like missing revenue, or hide an issue that deserves investigation.
Ask the financial and billing teams to agree on the reports that reconcile to the accounts. Keep the original exports and record the filters used. If a report can change as claims are resubmitted or payments are posted, retain a dated version so reviewers can reproduce the analysis.
Define the units of analysis as well. Are you reviewing encounters, claims, claim lines, service units or collections? Different denominators answer different questions. A denial percentage is difficult to interpret when one report counts claims and another counts individual lines. ABA due diligence and transition: an owner’s preparation guide
Write a short reporting note that a buyer can read before opening the files. It should explain the period, definitions, known system changes and material limitations. This saves repeated clarification and helps the review begin on the right basis.
Build the evidence chain before expanding the sample
For a selected service, identify the relevant authorization where required, the documented service, the submitted claim and the resulting payment or outstanding status. The appropriate reviewer should be able to trace the chain without relying on someone’s memory.
Check whether the dates, service details and relevant provider information agree across records. If something differs, record the difference and who will assess it. Do not assume that every inconsistency is an overpayment, and do not assume that a paid claim establishes complete compliance.
TRICARE’s Autism Care Demonstration, for example, states that ABA services require pre-authorization. That is a program-specific requirement; it should not be generalized into an identical rule for every payer. Build the review around the actual program and contract requirements that apply to each service. TRICARE Autism Care Demonstration
Start with a manageable sample to test the method, then let the qualified reviewers determine whether and how to expand it. A convenient sample can expose a process problem, but it does not establish an error rate for the whole practice. Avoid presenting limited testing as a formal assurance conclusion.
Keep authorization questions precise
Prepare a payer-specific summary of who manages authorizations, where records are kept and how expiration or changes are tracked. Include the escalation process when services or circumstances change. The buyer needs to understand the workflow as well as see documents.
When a record appears incomplete, distinguish among several possibilities: a missing copy, a timing issue, a service outside the authorization or a different requirement under the applicable payer policy. The distinction requires review, not an automatic label applied by a spreadsheet.
Clinical appropriateness and payment authorization are related considerations but not interchangeable judgments. Let clinical leaders address the care questions and the relevant billing or legal specialists address payment requirements. A transaction deadline should not compress those roles into a casual administrative decision.
If a requirement cannot be established from current files, document what is unknown and what source or reviewer is needed. A clear unresolved question is safer than filling a gap with an assumption that later gets repeated as fact.
Reconcile claims and collections to the financial story
Prepare a bridge from the billing system to the relevant financial reporting. Explain timing differences, adjustments, write-offs and other material reconciling items with your accountant. Keep the bridge consistent with the earnings period used in the sale materials.
Review aged receivables by meaningful categories. An old balance awaiting a routine administrative step is different from a repeatedly denied claim or a disputed amount. Do not assume every outstanding dollar will be collected merely because it remains on the report.
Identify subsequent receipts where they help explain the position at the review date, while labeling them clearly. A payment received later can provide useful evidence, but it should not be silently moved into the wrong reporting period to improve a presentation.
Ask what the accounting treatment assumes about collectability and what evidence supports it. If the buyer proposes a different view, reconcile the disagreement explicitly. The purpose is to understand sustainable earnings and cash behavior, not simply to defend the largest revenue figure.
Investigate denials without reducing them to one percentage
A single denial rate can conceal very different problems. Group issues by payer, reason, period and status where the data supports it. Separate corrected and paid items from unresolved items, and distinguish an initial rejection from a final nonpayment where the systems allow that distinction.
Look for patterns that suggest a process weakness. Perhaps authorization dates are not being tracked consistently, or a system change affected claim submission. These are examples of questions to investigate, not assumptions about your practice.
The HHS Office of Inspector General’s Indiana ABA audit identified improper and potentially improper Medicaid payments in the program and period it reviewed. It demonstrates why supporting documentation matters, but it is not evidence of the error rate in another practice or in ABA businesses generally. HHS OIG Indiana ABA payment audit
If review identifies a possible compliance or repayment issue, route it promptly to qualified counsel and the appropriate responsible team. Do not make a sale presentation the place where legal conclusions are improvised. Record the issue and the review status without minimizing or exaggerating it.
Show remediation as evidence rather than a promise
A buyer may ask what changed after a problem was discovered. Prepare a concise account of the cause identified, the action taken, the person responsible and the follow-up evidence. Distinguish completed changes from planned changes and from results that have not yet been tested.
Suppose, as an illustrative example, a practice finds that authorization renewals are being tracked inconsistently. Creating a new spreadsheet is an action. Assigning ownership and testing a defined period of follow-up shows whether the new process is being used. Neither step by itself proves that every historical claim was correct.
Keep remediation separate from the analysis of any financial exposure. Improving a workflow does not necessarily resolve past payments or eliminate a disclosure obligation. Ask the relevant advisers how those questions should be handled in the transaction.
Avoid changing or recreating clinical records to make an evidence package look complete. Any permissible correction must follow the applicable documentation requirements and preserve an accurate record. Have clinical and compliance leadership direct that process.
Protect sensitive records during buyer review
Begin with aggregated and appropriately limited information wherever it answers the buyer’s question. If more detailed records are needed, have privacy counsel establish the legal basis, scope, recipients and safeguards before disclosure. An NDA alone does not settle those requirements.
HHS describes the HIPAA minimum necessary standard as requiring reasonable efforts to limit applicable uses, disclosures and requests to the information needed for the purpose. Its exceptions and application require attention to the specific circumstances. Do not assume that a transaction team’s request is automatically permissible in its proposed form. HHS minimum necessary guidance
Use controlled access, named recipients and a record of what was shared. Consider whether identifiers can be removed or whether an appropriately restricted review can answer the question. Let qualified advisers determine the method rather than labeling information de-identified without checking the applicable standard.
Keep employee information under similar discipline. A billing review may need to understand roles or credentials without receiving unrelated personal details. Give reviewers enough lawful information to do the work, not every field available in an export.
Prepare a buyer-ready explanation of remaining uncertainty
Create an exception register that distinguishes facts from open questions. Useful fields include the issue, affected period, evidence location, responsible reviewer, current status and the next action. Where an amount is not yet established, say so rather than inserting a false zero.
Use plain language in the summary. A buyer should be able to understand whether a difference is explained, under review or awaiting information from another party. Keep estimates labeled and have the right adviser review any statement about financial or legal consequences.
When new evidence changes an answer, update the summary and tell the responsible transaction advisers. Version control matters because a buyer may otherwise compare an old explanation with new records and conclude that the inconsistency is unexplained. Preparing an ABA staff-retention plan for a transaction
The best preparation leaves a clear path from the sale narrative back to the evidence. It does not require every record to fit a perfect story; it requires the story to reflect the records honestly.
Frequently asked questions
What is ABA billing due diligence?
It is a review of the evidence connecting authorized and documented services, claims, collections and financial reporting in a potential transaction. Its scope should reflect the practice’s payers, systems and identified risks.
Does a paid claim prove the documentation is compliant?
No. Payment alone does not establish that all applicable requirements were satisfied. Qualified reviewers should assess the supporting evidence and the rules relevant to the service and payer.
Should I calculate one denial rate for the whole practice?
A summary may be useful, but define the denominator and distinguish reasons, payers and resolution status. One percentage can conceal important differences between corrected claims and unresolved nonpayment.
Can a small sample establish my overall error rate?
Not automatically. A limited or convenience sample can identify questions, but broader conclusions require an appropriate review methodology. Do not describe informal testing as a comprehensive audit.
What if authorization evidence is missing?
Record the gap, identify the applicable requirement and have the responsible team investigate. Distinguish a missing copy from a substantive authorization problem before drawing conclusions about payment or compliance.
Should detailed records go directly to the buyer?
Only through a process reviewed for the applicable privacy and disclosure requirements. Start with appropriately limited information, confirm the legal basis for more detail and use suitable access controls.
Connect billing evidence to the ownership handover
Return to ABA due diligence and transition: an owner’s preparation guide to see how billing fits with staffing, systems and operating continuity. Preparing an ABA staff-retention plan for a transaction covers another dependency: keeping the people and knowledge needed to operate the process through the transaction.
Before closing, make sure the agreed handover identifies who owns unresolved billing issues, access arrangements and follow-up work. Legal responsibility must follow the actual agreements and applicable requirements, not an informal assumption that the other side will handle it.
If you are preparing a sale and want to organize the questions a buyer is likely to raise, Olympic M&A’s behavioral health advisory page provides a route to discuss the transaction. Olympic M&A behavioral health advisory Bring the reporting definitions and exception log alongside the headline financials.